Introduction
A developer pitching a new office park in Bengaluru today does not lead with rent per square foot. They lead with the certification pathway, the retrofit plan, and the energy benchmarking data, because that is what the anchor tenant’s real estate committee asks about first. ESG in Indian commercial real estate has stopped being a sustainability slide at the back of the investor deck. It has become a line item in the underwriting model.
That shift did not happen through goodwill. It happened because occupiers, regulators and capital providers each independently started pricing it in, and the data now shows up consistently across all three.
ESG Trends in Indian Commercial Real Estate: What the Numbers Show
Green Certification Has Become the Baseline, Not the Differentiator
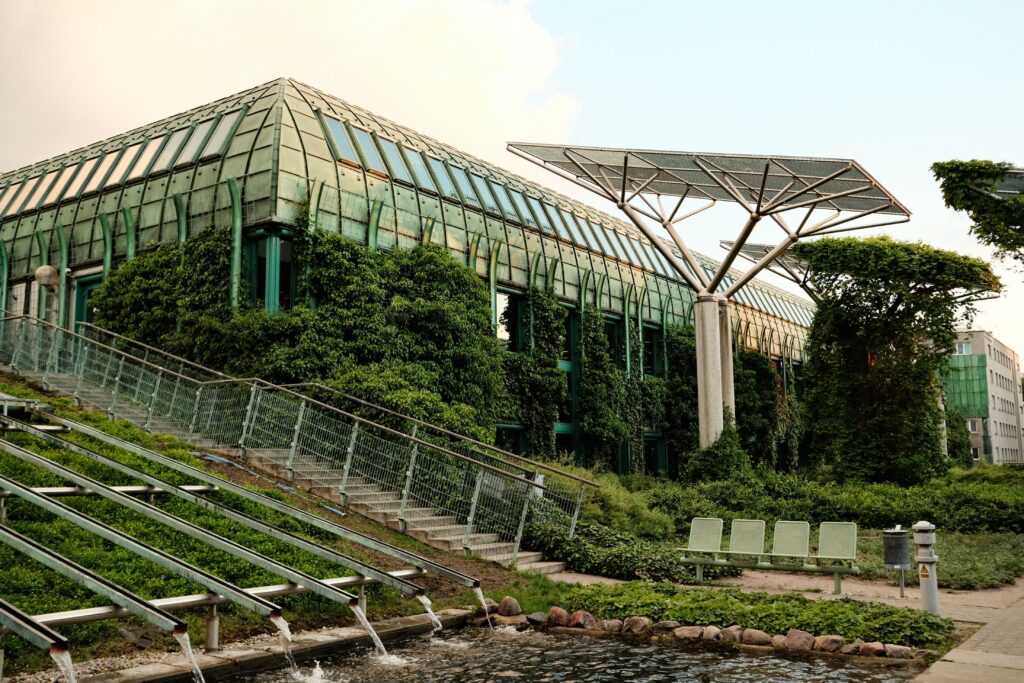
The scale of the shift is easy to underestimate if you have not looked at it recently. Colliers India’s 2026 office market outlook found that green-certified buildings already account for nearly two-thirds of India’s roughly 574 million square feet of office stock as of 2025, and more than 80% of new supply in 2026 is expected to be green certified, pushing overall green penetration to 70-75% nationally.
For a lender or investor, that number changes the framing entirely. A non-certified building is no longer a neutral choice sitting alongside a certified one. It is increasingly the minority asset in its own market, competing for a shrinking pool of occupiers who have not yet made certification a hard requirement.
Occupiers Are Setting the Pace, Not Just Responding to It
The demand side confirms this is occupier-led rather than developer-marketed. CBRE’s 2025 India Office Occupier Survey found that 63% of firms now have ESG goals specific to their real estate portfolio, and companies that have already secured certified space are moving on to broader concerns such as wellbeing and operational efficiency rather than treating certification as a finished task.
This matters for timing. Occupier ESG mandates set two or three years ago are only now showing up as leasing decisions, which means the demand curve for certified space is still climbing, not levelling off. A developer underwriting a project today against last cycle’s occupier preferences is underwriting to a market that has already moved.
The Retrofit Opportunity Sitting Inside Older Stock
ESG in Indian commercial real estate is not only a new-build story. Colliers’ India office demand forecast identifies over 420 million square feet of Grade A office stock older than 10 years that is not yet environmentally compliant, representing a retrofit and upgrade opportunity Colliers values at more than Rs 500 billion. That is a meaningful pool of existing assets where a repositioning strategy, not new construction, is the route to ESG compliance.
For a structured credit investor, this reframes what an ESG-linked real estate opportunity looks like. It is not limited to financing new green-certified towers. It extends to financing the retrofit of an older, well-located asset whose owner needs capital to upgrade systems, envelope and certifications to avoid losing tenants to newer stock.
The Regulatory Layer: BRSR and Climate Disclosure Are No Longer Optional
Regulation has caught up to market practice rather than leading it, but it has caught up meaningfully. SEBI’s Business Responsibility and Sustainability Reporting framework now applies to the top 1,000 listed companies by market capitalisation, with the more intensive BRSR Core disclosure requirements, covering roughly 30 assured KPIs on emissions, water use and safety, being phased in from the top 150 companies toward the full top 1,000 by FY2026-27.
On the lending side, the Reserve Bank of India has laid out a phased climate disclosure roadmap requiring scheduled commercial banks, all-India financial institutions and top and upper layer NBFCs to begin reporting governance, strategy and risk management disclosures on climate-related financial risk from FY2025-26, with detailed metrics and targets to follow from FY2027-28. For real estate developers and their lenders, this means the institutions financing a project are themselves increasingly required to account for that project’s climate exposure, which feeds back into how those loans get priced and structured.
Where This Shows Up in Deal Structuring
None of these changes the fundamentals of underwriting a real estate debt or structured equity position, but it does add a layer that a lender ignores at their own risk.
- Exit assumptions increasingly need to reference certified-comparable transactions rather than a blended market average, since certified and non-certified assets are starting to trade on different curves
- A retrofit-linked structured equity position, where capital funds an ESG upgrade in exchange for a coupon plus a share of the resulting rental uplift, is a genuinely different risk profile from ground-up construction finance and should be underwritten as such
- Developer-level BRSR or climate disclosure exposure is becoming a relevant diligence item even for privately held counterparties, since listed anchor tenants and lenders are increasingly asking their supply chain and borrowers for this data under value-chain reporting requirements
Metrics like IRR, MOIC and DPI still govern how a deal is evaluated. What has changed is that the underlying cash flow assumptions feeding those metrics now need to account for a certification or retrofit variable that did not meaningfully move the numbers five years ago.
A Note on What This Is Not
It is worth being direct about the limits of this trend. ESG certification is a design, disclosure and operational standard. It is not a guarantee of tenant demand, construction quality or developer solvency, and a well-certified building with a weak sponsor or a poor location can still underperform a conventional asset with strong fundamentals. The data above describes a structural tailwind for a specific category of asset, not a substitute for the underwriting fundamentals that determine whether an investment gets repaid on schedule. Forward-looking figures such as Colliers 2026 supply projections are directional estimates, not guaranteed outcomes, and should be read as such.
Conclusion
ESG in Indian commercial real estate has moved past the point where it can be treated as a marketing layer on top of a conventional deal. Green certification now covers roughly two-thirds of India’s office stock, occupier ESG mandates are still working their way into leasing decisions rather than having already peaked, and regulators on both the listed-company and lending side have built disclosure timelines that will keep tightening through FY2027-28. For IFAs, channel partners and family offices evaluating real estate private credit, the practical takeaway is that certification status, retrofit potential and disclosure exposure are becoming standard underwriting inputs, not a separate ESG conversation bolted onto the deal.